We’re starting a position in a cybersecurity stock that’s been in our Bullpen watch list

We’re starting a position in a cybersecurity stock that’s been in our Bullpen watch list

Sakorn Sukkasemsakorn | Istock | Getty Images

We’re initiating a position in Palo Alto Networks (PANW), buying 125 shares at roughly $175 each. Following Wednesday’s trade, Jim Cramer’s Charitable Trust will own 125 shares of PANW, starting its weighting in the portfolio at about 0.73{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}.

We’re calling up this leader in cybersecurity from the bullpen. We originally added PANW to our “stocks in waiting list,” which we call our Bullpen, last August around $167 per share. Since then, shares of Palo Alto Networks have gained roughly 4{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} compared to the S&P 500‘s decline of about 1{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}.

Much like the broader market, PANW went through a nasty decline back in December and has since rallied nicely so far in 2023. But even after this year’s gains, shares are still down from the $180s in late August and the low $200s it reached last April. We think the stock can return to those prior highs in time. 

With earnings on the horizon, we are intentionally starting our PANW position on the smaller side. The company is scheduled to report earnings this coming Tuesday after the closing bell on Wall Street. This buy isn’t a call on the upcoming quarter — but if the stock were to fall for any reason that did not change our positive long-term view, we would greet weakness as an opportunity to bulk up our stake.

Stock Chart IconStock chart icon

hide content

Palo Alto Networks (PANW) 1-year performance

We’re starting a position in Palo Alto Networks because of its leadership in cybersecurity. Earlier this week, Goldman Sachs published a research initiation note on cybersecurity companies. The analysts, who rated Palo Alto with a buy, said they expect “secular tailwinds in security to drive budget growth ahead of broader information technology (IT) spending and broader software over the next decade.” Goldman believes security will continue to take share of total IT and software budgets for three reasons:

  • Security consistently screens as the first priority for investment in Goldman’s bi-annual survey of chief investment officers.
  • Companies need to continue to invest in leading-edge technology to defend against threats.
  • The evolving threat landscape has grown increasingly complex as more companies increase digital transformation projects.

Under this favorable backdrop of spending and Palo Alto Networks’ leading multi-platform approach, Goldman believes the company is positioned for “durable growth” of around 20{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} for the next five years.

“We believe Palo Alto Networks is furthest along in the industry with executing a multi-platform strategy with technology leadership across several product vectors. Today, we view Palo Alto as a portfolio of network, endpoint and cloud products at different stages of product maturity, each leveraging centralized domain expertise in user interface/user experience (UIUX), marketing, security intelligence and machine learning.”

Cybersecurity isn’t completely immune to the weaker macro environment, but it should be one of — if not the — most resilient areas of enterprise spending. On the previous earnings call, management flagged how deals are starting to face more scrutiny and are taking longer to close. But on a more positive note, Palo Alto said it’s experiencing few deal cancelations. We do not think that changes no matter how tough things get in the economy.

If a threat were to arise, causing disruptions to your business, you don’t want to be the one that left the company vulnerable because you cut back spending on cyber.

Palo Alto Networks is also one of a handful of tech companies that has successfully made the pivot towards emphasizing profitability in this evolving macro environment. Management is doing an excellent job accelerating its efforts to drive incremental operating leverage. They have previously committed to 50 to 100 basis points of operating margin expansion and 100 to 150 basis points of adjusted cash flow margin expansion from fiscal 2022 through 2024.

There also could be a special catalyst on the horizon that could reward shareholders. Thanks to management’s push for profitability, Palo Alto Networks has delivered two consecutive quarters of GAAP (generally accepted accounting principles) profitability. If the next two quarters are also profitable, the company will meet all the requirements to be added to the S&P 500 index. We bring this up because a stock tends to jump when it gets included in the index due to the demand that is created by the mutual funds and exchange-traded funds (ETF) that are forced to buy the stock to keep their track to the index

To be clear, just because a company reports GAAP profits for four consecutive quarters it doesn’t guarantee a spot in the S&P 500. We would never recommend buying a stock solely on this basis. We buy stocks for fundamental reasons. However, the addition of Palo Alto to the index would be a nice bonus for shareholders based on the history of other stocks popping in reaction to the news.

We’re initiating our PANW position with a price target of $200 per share, about 15{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} higher than current levels, representing roughly 49.5-times fiscal year 2024 earnings-per-share consensus estimates. The knock on PANW is obviously that it is an expensive stock on earnings. But if the company continues to handily beat expectations, then the stock will prove to be much a much better value than what it has appeared. Additionally, as the leader in cybersecurity, it’s consistent 20{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} grow is more defensible than other areas of tech, which are experiencing problems from economic weakness.

(Jim Cramer’s Charitable Trust is long PAWN. See here for a full list of the stocks.)

As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade.

THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY, TOGETHER WITH OUR DISCLAIMER.  NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB.  NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.
Akamai Stock Tumbles on New Cloud Computing Push

Akamai Stock Tumbles on New Cloud Computing Push

Akamai Technologies is making a bet that it can compete head-to-head with the giant in the cloud computing market, and investors are not sure they like the idea.

Akamai (ticker: AKAM) posted fourth-quarter results late Tuesday, and the stock inched higher after hours. But the company’s guidance for both the quarter and the full year fell a little short of Wall Street estimates, and analyst reaction to the quarter was chilly.

The decline has less to do with the results than the company’s shifting business priorities. Akamai has three primary businesses. It was a pioneer in content delivery networks, which websites use to improve their performance. It provides security software, in a natural extension of that CDN business. And starting with the company’s $900 million acquisition of Linode in March 2022, Akamai expanded into the vast but hypercompetitive cloud computing market. 

Now Akamai is going all in on the cloud—CEO Tom Leighton told Barron’s in an interview on Tuesday that he thinks the cloud business will eventually account for the majority of Akamai’s revenue.

There were a few other issues with the report. While content delivery network revenue was better-than-expected in the quarter, for instance, security software revenue missed estimates, and Wall Street analysts were also overly optimistic about the growth of the security business for the full year.

But the big issue is that Akamai is going to boost capital spending substantially to build out its cloud arm. Earlier on Tuesday, the company unveiled the Akamai Connected Cloud, along with plans to sharply increase its roster of cloud computing sites in 2023. Guggenheim analyst Ramond McDonnough, who maintains a Sell rating on the stock with a $75 target price, points out that Akamai expects heavy capital spending this year as a percentage of revenue—21{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, compared with the Wall Street consensus forecast of 14{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}.

RBC Capital analyst Rishi Jaluria responded to the report by cutting his rating on the stock to Sector Perform from Outperform, while chopping his target price to $85, from $100. “The major story of the earnings call…was the clear change in strategy in going all-in” on cloud computing, he wrote. “We shift to the sidelines as we believe this move alters the risk-reward profile, and we would wait for evidence it can pay off before getting back involved.”

Among other concerns, Jaluria notes that Akamai seems intent on competing with the large cloud players—Amazon’s (AMZN) AWS, Microsoft’s (MSFT) Azure, and Alphabet’s (GOOGL) Google Cloud—on price. “If Akamai is successful, hyperscale cloud vendors can cut prices themselves,” he writes.

Needham analyst Alex Henderson, who maintains his Hold rating on Akamai shares, thinks investors will view the company’s shift in focus to cloud computing from security as a “lower visibility strategy,” which will involve a multiyear transition, starting with an intense investment phase.

Akamai shares on Wednesday are down 9.8{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, to $79.18, making it the second worst performer in the S&P 500 on the day, behind Devon Energy (DVN).

Write to Eric J. Savitz at eric.savitz@barrons.com

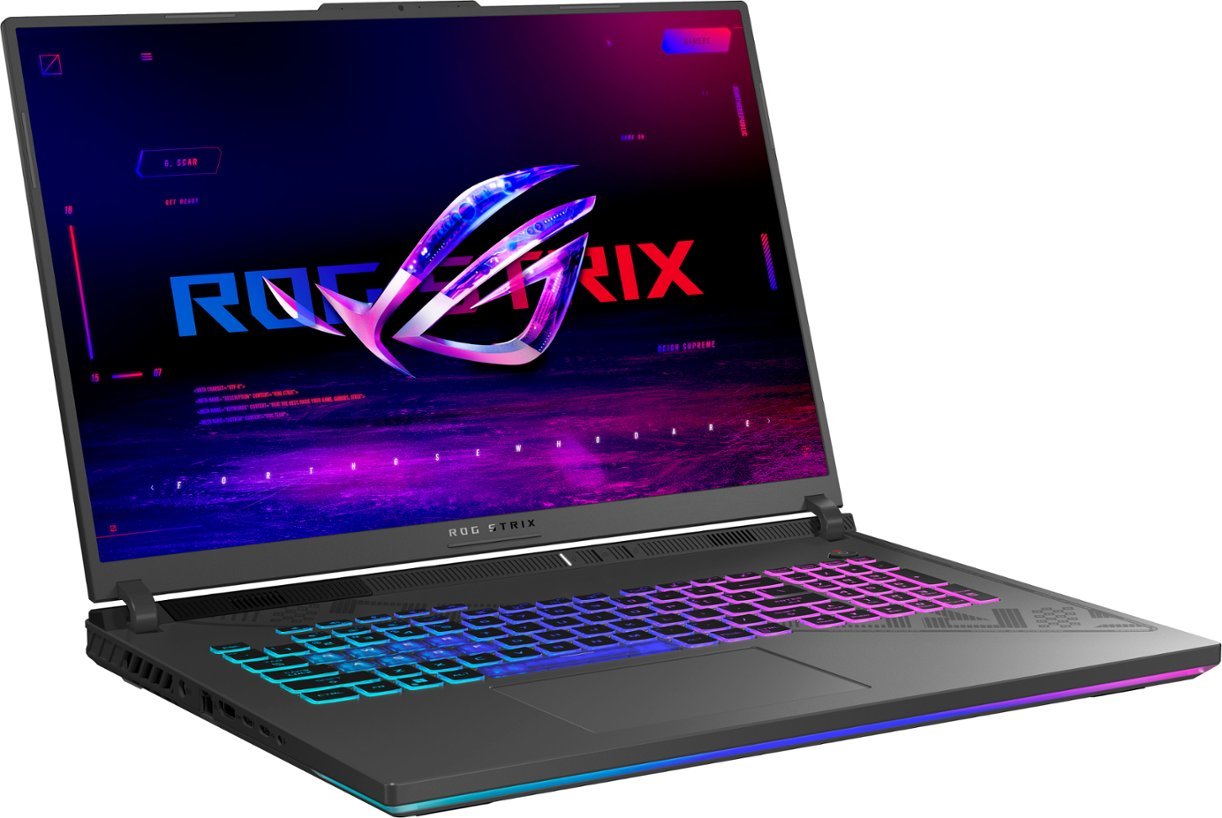
Asus ROG Strix G18 featuring Intel’s i9-13980HX and Nvidia’s RTX 4080 dGPU blows competing laptops out of the water with unbeatable US$2,499.99 launch price

Asus ROG Strix G18 featuring Intel’s i9-13980HX and Nvidia’s RTX 4080 dGPU blows competing laptops out of the water with unbeatable US,499.99 launch price

BestBuy has the Asus ROG Strix G18 gaming laptop on sale proper now for US$2,4999.99. The configuration consists of the most powerful cellular processor from Intel’s Raptor Lake-HX sequence – the i9-13980HX – coupled with 16 GB of DDR5-4800 RAM and a 1 TB PCIe 4. NVMe SSD as well as the Nvidia RTX 4080 mobile GPU with 12 GB VRAM. Granted, it is not just a discount, but as opposed to other similar configurations from competing OEMs, this is by considerably the most very affordable.

For reference, the closest competitor would be the Alienware M18 at US$2,900, adopted by the Acer Predator Helios 18 at US$3,000, when the Razer Blade 18 appears way overpriced at US$3,800. Also, all 3 competitors sport a little bit significantly less highly effective processors. Not to mention that the Strix G18 completely destroys all cell RTX 3080 Ti configurations (on average 25-30{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} slower) that still sell for a lot more than US$3,000 now.&#13

A value this lower could be indicative of some compromises. Nevertheless, this does not seem to be to be the situation with the Strix G18. Even though some would argue that DDR5-4800 could be considerably slower than the DDR5-5600 modules, youtuber Dave2D statements that the change is not truly visible. The display screen is not bad at all, either. In point, Dave2D thinks this could be 1 of the ideal 18-inch 2560 x 1600 240 Hz IPS panel out there, as it is extremely dazzling at 489 nits, has respectable colour copy with 99{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} DCI-P3 and also attributes a MUX change.&#13

Admittedly, there are a few shortcomings with this design, but nothing that could have an affect on the total effectiveness. Dave2D details out that biometrics are entirely missing here, and the 18-inch size together with the significant 330 W adapter may well detract from the portability component. For individuals with sensitive hearing, the Strix G18 could show some coil whine coming from the GPU VRM when less than load.&#13


Buy the Asus ROG Strix G18 gaming laptop from BestBuy

Fortnite update 23.40 PATCH NOTES, server downtime, Most Wanted, Witcher School of Llama | Gaming | Entertainment

Fortnite update 23.40 PATCH NOTES, server downtime, Most Wanted, Witcher School of Llama | Gaming | Entertainment

Fortnite admirers are counting down to the launch of update 23.40 on PS4, PS5, Xbox Sequence X/S, Xbox One, Laptop, Android and Nintendo Swap. The future important Fortnite update has a February 14 release day and a 9am GMT British isles start time. Useless to say, as a numbered update, the activity will be taken offline for server routine maintenance, commencing when matchmaking is disabled at 8.30am GMT, and ending when the servers appear again on the net at about 11am.

The news was introduced by Epic Games on Twitter, alongside a teaser about what fans can count on.

“Get ready to crack open up the vault tomorrow with Update v23.40!” reads an Epic tweet. “Downtime commences at 4 AM ET, with matchmaking staying disabled shortly right before.”

Dependent on Epic’s tweet and recent leaks, it appears to be like like update 23.40 could introduce some kind of most desired prison method, or it’s possible even a vault heist.

That’s on top rated of the common array of new skins, not to point out further augments, new quests, unvaulted objects and lots a lot more.

Epic will also increase the next Faculty of Llama Path, which benefits players with the Geralt of Rivia Foyer Track on completion.

Convey Online will update this report with all the new cosmetics and gameplay characteristics when downtime starts.

In the meantime, verify out the update 23.40 patch notes beneath.

Fortnite update 23.40 patch notes

General fixes

• The Sparkle Expert outfit is not reflective and shiny.

– The Sparkle Specialist outfit does not look sparkly/shiny and in its place appears matte.

• Sarah Connor’s Resistance Chief style has a stretched encounter.

– The Resistance Leader type for the Sarah Connor outfit seems to have a stretched encounter when executing some Emotes or steps.

• Players are unable to assert the Exile variation of the Mind’s Eye back bling

• Sub mode find screen could surface blank.

– Immediately after earlier picking a Group Sizing or Fill Get together selection from the method select screen, players may well be introduced with no options to change.

Battle Royale and Zero Establish fixes

• School of Llama banners lacking/greyed out

– We are conscious that banners been given from finishing School of Llama issues may well be missing from the Locker or “Equip” may perhaps be greyed out.

• “Shadow Strike” Augment temporarily disabled.

– The Shadow Striker Augment and have quickly disabled it from the pool of unlocked alternatives. It might still surface and unlock when a player initial discovers it.

• The “Icy Slide” Augment description is incorrect.

– The description of the “Icy Slide” Increase incorrectly claims you get a pace raise after sliding, when you basically get a velocity enhance although sliding as intended.

• Peely’s Plunder might direct to treasure in inaccessible locations.

– Players may possibly locate the Peely’s Plunder increase can often direct them to treasure in an inaccessible space.

Creative fixes

• Help you save System may well reset participant scores and other stats

– The Save Product could reset participant stats if players are enjoying your recreation for the duration of your video game update. through your activity update.

• Tiles can grow to be invisible in shade change sport mode

– We are conscious of an challenge where by tiles may turn into invisible in color switch game modes.

Cellular fixes

• Some gadgets may perhaps be capped to 60 FPS in spite of picking 90 FPS

– Some Android units may obtain that in spite of obtaining 90fps as the selected framerate, it will get capped at 60 FPS.

Sector-specific large deals return for Indian IT services companies

Sector-specific large deals return for Indian IT services companies

Prime Indian IT solutions firms are witnessing an uptick in massive and mega discounts in particular sectors like banking, economical services and insurance plan (BFSI) as they flip to technological know-how to optimise fees in the present uncertain financial surroundings.

Past 7 days, Tata Consultancy Companies (TCS), the country’s largest IT expert services agency, introduced an in excess of £600-million (about $723-million) agreement with Phoenix Group, UK’s major lengthy-expression price savings and retirements company, to digitally transform the latter’s ReAssure enterprise making use of the TCS BaNCS-primarily based platform. The deal is an expansion of TCS’s lengthy-standing partnership with the Phoenix Team.

Typically, leading-tier IT corporations consider discounts really worth $100 million or more as big promotions and all those additional than $500 million are referred to as mega discounts. For TCS, these kinds of mega discounts are returning just about following 4 years.

Also examine: US CPI facts for January released, inflation falls fewer than marketplace expectations

In 2018, TCS signed a contract value far more than $2 billion in revenues with Transamerica, a major service provider of daily life insurance policy, retirement and expense remedies, to allow the transformation of administration of its US insurance coverage and annuity business enterprise strains. In the very same yr, TCS expanded a offer with Uk-centered insurance provider M&G Prudential taking the deal benefit to more than $1.2 billion in 10 several years.

“There will be some substantial deal initiatives as the present macroeconomic situation develops and shoppers want to optimise charges as well as provider consolidation procedures experienced, related to the pandemic where by we saw a one particular-time maximize in substantial discounts. This is likely to be induced by account or sector-distinct concerns and not a modify in offer tendencies for the extensive term…We see BFSI firms generally getting major measures in a economic downturn or financial downturn to optimise fees,” stated Nitish Mittal, spouse, Europe Technologies Follow, Everest Team.

Infosys signed 32 significant offers worthy of a total agreement benefit (TCV) of $3.3 billion in Q3, the greatest in the last eight quarters with 36{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} web new. Of the full amount of offers, 7 substantial bargains were being in retail, six each in fiscal companies and communications, 5 each and every in strength, utilities, sources & companies (EURS) and producing, two in life sciences, and a person in hello-tech.

“We see good traction of significant deals, and we have found more and extra relevance, link with our clientele on the price efficiency and automation performs,” Salil Parekh, CEO and MD, Infosys, explained throughout the Q3 earnings.

Also browse: Apollo Hospitals Convenes Global Health Dialogue Highlights vital challenges in affected individual safety

Wipro signed 11 substantial offers with a TCV of about $1 billion for the duration of Q3. “Our pipeline of massive deals is both of those strong, and diversified…Our big discounts involve new and current purchasers searching for a transformation spouse, or going by way of seller consolidation,” Thierry Delaporte, CEO and MD, Wipro said in a publish earnings get in touch with.

“Indian IT gamers stand to obtain market place share amid this macro slowdown due to clients’ large aim on expense optimisation and efficiency enhancement (noticeable in the pick-up in agreement activity during Q3 FY23), in excess of much more discretionary expend on electronic transformation,” analysts at ICICI Securities said.

The good and bad of ‘zero-touch’ cloud operations

The good and bad of ‘zero-touch’ cloud operations

Zero-contact cloud functions is the concept of automating cloud operations (cloudops) procedures to minimize the require for human intervention. Exclusively, it includes automating the deployment, configuration, scaling, monitoring, and resolution of concerns on all cloud platforms (community and non-public), and even extends to common legacy programs and edge computing techniques as effectively.

Bodily, it is a layer of technology working earlier mentioned the cloud suppliers (e.g., a metacloud). It can be something which is equipped to automate cloudops, for instance, AIops technological know-how, id management, performance administration, governance, and finops. This consists of detecting issues and resolving them without human participation. 

Adopting a metacloud also means significantly less urgent operational processes, such as typical routine maintenance tactics (like all those surrounding catastrophe restoration). Devops toolchains also use these varieties of systems for the exact applications.

Like any good engineering movement, there are upsides and there are downsides to take into consideration. Let’s seem at equally.

Fantastic news

Fundamentally, zero-contact cloudops delivers a couple of perfectly-recognized positive aspects:

  • Better performance. Automating program tasks in cloudops frees up time and resources for cloud teams to aim on extra strategic initiatives.
  • Significantly less error. The the vast majority of occasions that a little something goes erroneous, a human has screwed it up. Zero contact minimizes the danger of human mistake.
  • A lot quicker time to deployment. Automating deployments and scaling cloud providers compresses the thought-to-deployment timeframe.
  • Improved uptime. By making use of AI-based mostly algorithms to predict troubles before they come about (these types of as happens in AIops), cloud groups can proactively take care of difficulties and enhance uptime.
  • Superior collaboration. Integrating devops techniques into cloudops can enhance collaboration involving progress and functions teams, with all the noticeable rewards.

Bad information

Of course, the fantastic news requires to be balanced with the realities that handful of are speaking about these days.

  • Absence of manage. Automating program tasks in cloud administration can lessen the amount of handle that cloudops teams have in excess of the surroundings. Several cloud architects go through from the worry of automation but they do make some legitimate details.
  • Loss of cloudops expertise. If we are not straight controlling cloudops most of the time, how will we learn to fix issues when individuals are essential? Zero-touch cloudops could final result in complacency. This could guide to a disaster when correct human skills are needed but no one’s completed any real cloudops perform for several years.
  • Balancing automation with human oversight. Most organizations err on one intense or the other: Possibly individuals are never ever involved or they are entirely involved. The truth is that zero contact nonetheless necessitates oversight from individuals, but a stability must be located.
  • Dependence on know-how. The double-edged sword is that technologies can strengthen effectiveness and minimize threat, but it can also introduce new challenges and difficulties if it fails. Quite a few teams only target on the added benefits. Some chance nonetheless exists, or net-new possibility can be released by zero-touch cloudops.
  • It is highly-priced. Employing zero contact will come at a high price—not just the technologies, but also the talent and organizing to pull it off successfully. Generally, I see enterprises try to do it on the low-priced and make things even worse. If you assume the expense price savings that may possibly result will fund a zero-touch transformation venture (I hear this frequently), you are likely to be dissatisfied.

Really worth the time, hazard, and money?

I’ve focused largely on the downsides of zero contact in this article. A lot of other pundits and know-how suppliers will not. I’m trying to carry all the info to the table for your consideration. For most enterprises, investment decision in zero-touch cloudops, which include constructing a audio metacloud technological know-how layer, will in fact deliver a wonderful offer of benefit back again to the company.

Even so, achievement is mostly area-unique, as to what you do and what answers you develop. No canned zero-contact options nonetheless exist, while lots of vendors are boasting theirs do in their income collateral. It demands scheduling and heaps of high priced smart people today to arrive up with the appropriate resolution. I propose you either make the financial commitment essential or don’t trouble.

Ideally, I have decreased your anticipations a bit but also amplified your odds of achievement with zero contact.

Copyright © 2023 IDG Communications, Inc.