Here are five points in tech that happened this week and how they have an impact on your company. Did you skip them?
1 – Google shows off far more of what its ChatGPT competitor Bard can do.
Subsequent-level online lookup features were introduced on a livestream in Paris on Wednesday. Bard – Google’s reply to Microsoft’s OpenAI’s ChatGPT – was demonstrated by Prabhakar Raghavan, Senior VP at Google. Applying the instance of buying an electrical vehicle, Raghavan demonstrated how Bard can support buyers slender down possibilities by offering complete information and facts, these as “the pros and cons” of electrical autos. Google CEO Sundar Pichai indicated that Bard is currently being made with synthetic intelligence—but it would require vigorous screening. Pichai will also involve personnel to examination the know-how so programmers can appropriate any flaws right before its official start. (Resource: CNBC)
Why this is vital for your business:
This stuff’s for actual, folks and you know Google is quaking. ChatGPT is previously enormously disrupting the lookup market. Could this be the conclusion for Google’s monopoly? Will tiny companies truly get some other choices when we want to advertise online?
2—Bing – indeed, Bing – just designed search interesting again.
Microsoft is leveling-up its research perform Bing with artificial intelligence—allowing internet people to not only do standard searches but chat with ChatGPT. Execs at Microsoft are psyched to display off Bing’s A.I. abilities. Microsoft has targeted its efforts to being a feasible competitor of Google since 2019 when it initially invested in Open up AI – $10 billion in accordance to stories. Bing is remaining utilized by a little team of testers but will become extra greatly offered. An case in point that was cited – looking for a vegetarian dinner menu where Bing will not only record menu items—that will seem on the left side of the user’s screen—it can create up a grocery list by isle and quantities essential for a specified quantity of people. (Source: New York Periods)
Why this is essential for your enterprise:
Microsoft has been attempting to contend with Google in the research business for several years. ChatGPT is now levelling the enjoying subject. Like I stated above, this could be a large reward to small firms as Microsoft and with any luck , other folks making use of ChatGPT’s conversational AI will be capable to supply choice on the internet advertising and search options for us.
3 – Apple expands tests of ‘buy now, spend later’ service to retail staff.
Apple Pay Later – a provider that provides prospects the choice of installment payments for buys – is staying tested according to workforce of the organization. Mark Gurman documented the services was declared to their consumer-base very last summer time though complex concerns prevented a tumble 2022 roll out for the iOS 16. Apple has analyzed the provider with company employees and is performing to start a invest in now, pay out later attribute this yr Bloomberg indicated. (Supply: Bloomberg)
Why this is vital for your company:
If I was running a smaller sized BNPL assistance I’d be really involved ty this. For little organizations it wouldn’t shock me to see Apple’s BNPL become our primary platform for this style of financing. Before long, of class, to be followed by Google, right?
4 – Cyber Insurance—a should-have for smaller company.
Cyber-attacks are getting to be far more advanced. Compact corporations have to be equally intense in defending versus ransomware. “You need safety experts to respond in the most effective way feasible,” Jason Rebholz – CISO at Corvus Insurance coverage – reported on the challenge of rising ransomware attacks. (Resource: Information Protection)
Why this is important for your enterprise:
In accordance to the Information Stability piece, despite the fact that these protection threats are escalating – in a 2021 study CNBC confirmed that only a quarter of tiny corporations mentioned they had cyber insurance policy. One option now on the sector is Guardz – a organization that expert services compact corporations in defending against cyber threats. Dor Eisner, the company’s CEO – feels cyber insurance policy will be industry typical in the subsequent ten years.
5—Shipt announces accelerator system to improve regional compact business progress in 5 towns
Shipt is exemplifying its community-focused initiatives through LadderUp —a software built to enable staff compete and thrive in the marketplace. Specially targeted on LBGTQ+ and people of color—Shipt is investing its time and initiatives by offering assistance to assist these demographics elevate their existence and “build up their capabilities to generate much healthier, a lot more resilient and equitable communities,” the business said. (Supply: Cision PR Newswire)
Why this is vital for your business:
The aim of LadderUp is to equip tiny business owners with understanding and perception to compete in today’s natural environment. Shopify announced it will husband or wife with Shipt. Applications are open now in five metropolitan areas: Atlanta Birmingham, AL Detroit Houston and Washington, D.C
Microsoft (MSFT), America’s next most worthwhile business, might say cloud expansion fell to its slowest price in five many years in the most latest quarter, the grim economy’s counterpoint to Major Tech’s flashy new merchandise.
Crucial Takeaways
Microsoft is set to report its next consecutive y-o-y earnings decrease.
Investors will dig for the overall performance of Clever Cloud and the ChatGPT outlook.
CEO Satya Nadella promised additional detailed strategies in this launch.
The Redmond, Washington-centered firm is envisioned to report earnings of $16.7 billion, or $2.24 cents a share, efficiently unchanged from the prior-12 months quarter, in accordance to estimates compiled by Visible Alpha. Revenue is predicted to maximize 3{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} 12 months-over-year to $51.1 billion. The firm will report fiscal outcomes for the third quarter of its 2023 fiscal year immediately after marketplaces shut Tuesday, April 25.
Traders will focus on the Clever Cloud segment, which has been Microsoft’s premier in each and every of the past eight quarters. Cloud profits is envisioned to grow at its slowest fee in 5 a long time, rising 15{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} to $21.9 billion. International paying on cloud services is projected to hit a record $592 billion in 2023, a 21{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} enhance from previous yr, in accordance to study agency Gartner.
Nevertheless, Microsoft’s cloud company could be a shiny location as the business is projected to post a double-digit revenue decrease in its Personal Computing segment, which consists of Windows products and solutions and products like the Surface area pill and Xbox gaming console.
Microsoft CEO Satya Nadella is anticipated to encounter inquiries about the future of Microsoft’s AI equipment and the impression of value-slicing measures. Nadella is most likely to base a great deal of the company’s outlook on the drive to AI.
“The future key wave of computing is being born, as the Microsoft Cloud turns the world’s most advanced AI products into a new computing platform,” he claimed in previous quarter’s earnings releases.
Microsoft extended its partnership with ChatGPT creator OpenAI in January, investing a documented $10 billion in the get started-up that has been privately valued at $29 billion. Microsoft’s AI-enhanced lookup motor, Bing, surpassed 100 million everyday active consumers for the 1st time in March. Even with the excitement, analysts are anticipating look for and advertisement profits to grow just 4{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} in the past quarter, compared with 22{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} development in the very same period a yr back.
Nadella will also offer updates on the layoffs declared in Microsoft’s last earnings update when the corporation described its initial fall in altered earnings in eight years. Operating expenses are forecast to increase 10{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, down from 18{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} in the past quarter.
Microsoft inventory touched a 14-yr large lately, up 20.40{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} on the year. The stock is marginally ahead of the S&P500 Facts Technological know-how index, up 20.13{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} in that period by comparison.
Xbox Video game Pass is Microsoft’s pay out-monthly subscription services presenting hundreds of video games and access to Xbox cloud streaming.
Considering the fact that it introduced in 2017, new users were being offered a thirty day period for just $1.
In excess of the weekend, people started to recognize that the promo presenting seems to have arrive to an stop.
Update (March 26, 2023 at 5:30 p.m. PT / 8:30 p.m. ET): Microsoft has responded to our ask for for remark and affirmation, giving the adhering to statement:
“We have stopped our preceding introductory give for Xbox Activity Go Top and Personal computer Match Move and are evaluating distinct advertising promotions for new members in the future.”
Our first story is below.
It may well be the conclusion of an period, as Microsoft calls time on Xbox Match Pass’ famed $1 promo time period.
Xbox Sport Go is Microsoft’s groundbreaking Netflix-like membership assistance, providing hundreds of game titles for a comparatively minimal monthly cost. As an alternative of spending countless numbers of dollars on a number of complete-priced AAA titles, Xbox Game Go spreads the value from just $10 for each thirty day period, and at bigger tiers, even comes with Xbox cloud streaming accessibility for gaming on the go.
Given that Xbox Recreation Pass released, new customers had been presented a thirty day period for just $1 to try out the services, but more than the weekend, customers started out to notice (by means of xgp.pl) that the long-time promotional pricing would seem to be gone.
(Impression credit score: Xbox.com | Windows Central)
Making an attempt to indicator up to Xbox Activity Pass (opens in new tab) using a fresh Microsoft account no extended delivers you access for $1. Rather, it hyperlinks straight to the a few present tiers, either $10 per month for Xbox Recreation Move on console, $10 for every thirty day period for Xbox Game Pass on Computer system, or $15 for each month for entry to the two and Xbox Cloud Gaming. From what we can convey to the adjust seems to be world wide, with no mention of the $1 promo tier showing in any nation we have tested out.
It makes sense that Microsoft would start winding down this advertising, as the user acquisition period is likely coming to an close. Adequate people today in all probability know about Xbox Recreation Move at this point for expansion to arise organically, notably so when you component in the volume of approaching Xbox video games hitting the services. Microsoft might also want to steer clear of a situation exactly where countless numbers indicator up for short-term one-month throwaway accounts to stay clear of acquiring to pay for future very predicted titles like Starfield. Starfield is among the the most expected video games of the latest memory, crafted by the staff at the rear of megahits like Fallout 4 and Elder Scrolls V: Skyrim. Microsoft is also expecting to near its deal for Activision-Blizzard, which will lead to key game titles like Phone of Duty and Diablo IV also hitting the provider. Preventing a circumstance the place tens of 1000’s indicator up to short term accounts for just $1 is probably a higher priority for the workforce.
We’ve arrived at out to Microsoft to get really hard affirmation as to whether or not this is in error, but I’d suspect that the organization has known as time on the promo, as the company has matured. Microsoft is also slowly and gradually rolling out Xbox Sport Move for Family members and Mates, giving up to 5 Xbox Sport Move Final accounts for around $25. As such, accessibility to Xbox Sport Pass will possibly be cheaper than at any time.
BRUSSELS, March 30 (Reuters) – Alphabet’s (GOOGL.O) Google Cloud has accused Microsoft (MSFT.O) of anti-aggressive cloud computing procedures and criticised imminent offers with several European cloud distributors, stating these do not remedy broader worries about its licensing conditions.
In Google Cloud’s 1st community opinions on Microsoft and its European bargains its Vice President Amit Zavery instructed Reuters the firm has lifted the concern with antitrust companies and urged European Union antitrust regulators to just take a nearer appear.
In response, Microsoft referred to a blogpost in May well final 12 months exactly where its president Brad Smith claimed it ‘has a wholesome range two placement when it arrives to cloud companies, with just around 20 percent current market share of international cloud services revenues’.
“We are committed to the European Cloud Local community and their achievement,” a Microsoft spokesperson informed Reuters on Thursday.
There is intensive rivalry involving the two U.S. tech giants in the rapid-increasing, multi-billion-dollar cloud computing business, the place Google trails marketplace chief Amazon (AMZN.O) and Microsoft.
The sector has not long ago drawn increased regulatory scrutiny, which include in the United States and in Britain, because of the dominance of a couple of players and its ever more critical purpose as additional and far more companies change their services to the cloud.
Microsoft has supplied to change its cloud computing methods in a offer with a few more compact rivals which in flip will suspend their antitrust issues, a individual with immediate know-how of the make a difference explained to Reuters this week.
The shift will stave off an EU investigation.
“Microsoft certainly has a incredibly anti-aggressive posture in cloud. They are leveraging a good deal of their dominance in the on-premise organization as effectively as Business 365 and Home windows to tie Azure and the rest of cloud products and services and make it really hard for customers to have a choice,” Zavery said in an job interview late on Wednesday.
“When we converse to a large amount of our prospects, they find a lot of these bundling procedures, as nicely as the way they develop pricing and licensing limitations, make it hard for them to decide on other vendors,” he additional.
‘UNFAIR ADVANTAGE’
Zavery mentioned specific bargains struck with various smaller sized European cloud suppliers only benefit Microsoft.
“They’re selectively form of buying out these kinds who complain and not make individuals conditions out there to absolutely everyone. So that absolutely makes it an unfair advantage to Microsoft and ties the people who complained back to Microsoft in any case,”
“No matter what they are presenting, there need to be phrases throughout for everybody, not just for one particular or two they’ve selected and pick, and that shows you that they have so significantly industry ability they can variety of go and do individuals factors separately.”
“My level to the regulators would be that they must look at this holistically, even although just one or two vendors might settle will not fix the broader issue. And that’s the problem we want to actually resolve, not unique vendors’ problems.”
The European Commission declined to remark.
Microsoft nevertheless faces yet another EU antitrust complaint from CISPE, whose customers consist of Amazon. The trade group has rejected the Microsoft’s variations.
Zavery dismissed the suggestion that the issue is simply a spat among Google and Microsoft.
“The dilemma is not about Google. I just want to make it incredibly apparent. It can be the cloud. The premise with cloud was to have an open, versatile way to deploy your computer software and have buyers additional decisions so that they can operate their software program in any position they select to in a substantially extra straightforward way,” he said.
Reporting by Foo Yun Chee Editing by Alexander Smith
As a result of covering the top cloud computing companies in the market, I wanted to share with the readers at Seeking Alpha an overview of the cloud computing market and why I believe this space provides attractive investment opportunities. Readers can see that I have a buy rating on Amazon (NASDAQ:AMZN), Microsoft (NASDAQ:MSFT), and Alphabet (NASDAQ:GOOGL). One of the main reasons for these ratings is their strong presence in the already sizeable and growing cloud computing market. Given this market is driven by the increasing demand of data storage and processing capabilities, the runway for growth is still considerable. Further to this, there is already solid data backing the stable revenues and high operating margins some companies in this space are able to achieve. This space is also changing some of the biggest companies in the world as a result of their cloud computing segments being their fastest growing segments and contributing to a sizable portion of their operating incomes. Furthermore, the cloud computing market has high barriers to entry with multi billion dollar investments needed in order to possess the scalability, efficiency, footprint, and capabilities to offer the best-in-class services. This results in significant competitive advantages for well-established technology companies such as AMZN, MSFT, and GOOGL. Let´s take a look into what really is cloud computing. I hope you enjoy the read!
What is Cloud Computing?
Let’s start with the basics. What is cloud computing? Cloud computing is essentially a network of servers around the world acting as a huge hard drive. Before the cloud existed, companies and individuals needed to back up their information and data into external devices, meaning a different hard drive. Nowadays, all this information and data can be transferred into the cloud, making it much more efficient and convenient for companies and individuals. One of the main benefits of the cloud is the accessibility to data and information remotely from anywhere in world at any given time as long as you have an internet connection. Companies and individuals also do not have the constraint of having too little storage, as in the cloud you can essentially store all the data you want and need.
Most of the cloud services offered are based on a subscription model meaning there is a monthly fee paid by customers. The beauty of this model for customers is that they are able to scale up or down their costs as they see fit. So, the more they use the cloud the more they will need to pay, while the less they use it the lower their costs will be.
So, why do companies want to move to the cloud instead of managing their data on premises? Of course, the main reason is to save money. Instead of having to build and power their own data centers and pay employees to operate them, companies can instead save time and effort by simply paying a cloud provider for this service. This also gives companies flexibility. Given the cloud can be used as they see fit, they can use it more during certain months or less during quite times. This gives companies the flexibility to adjust to their own needs.
How do cloud providers generate revenues?
Cloud computing is and has been a booming market for about a decade now and is likely to continue growing. For reference the global cloud computing market is projected to reach over $1.2 trillion by 2027. As such companies of the likes of AMZN, MSFT and GOOGL are all vying for a piece of the market. But how do these companies generate revenues from the cloud? As previously explained, the cloud model is a subscription model where companies can choose to subscribe to various services and pay as they go, meaning they pay depending on the usage of the services. There are several ways cloud providers generate revenues from cloud services, going from data storage, data transfers, cyber security, etc. According to tech researcher Gartner (IT), MSFT and AMZN have the most complete ecosystems of software and partnerships with third-party software-as-a-service providers.
Competitive Landscape
At the moment it is clear that cloud computing is truly dominated by two companies, AMZN with its AWS business recording revenues during the trailing twelve months (“TTM”) of $80.1 billion and MSFT with its cloud segment recording TTM revenues of $81.8 billion. Nonetheless, there is a distant third making strides to become a worthy opponent to these cloud giants. I am talking about Alphabet, a company with its Google Cloud business that has doubled revenues within two years and shows no sign of stopping. Although at a very distant third, Google Cloud has just reported revenues during the last twelve months of $26.3 billion and experienced a 37{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} growth rate year on year. Although Google Cloud is still a third of the size compared to AWS or MSFT Intelligent Cloud segment, it should not be left out as a top competitor in the space.
To understand why Google Cloud is a true competitor in the space, let´s take a look at AWS during 2018. At the end of 2018, AWS had very similar numbers to Google Cloud with revenues at approx. $26 billion showing growth rates of 50{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}. Yes, the growth rate was higher than Google Cloud’s 37{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, but it just goes to show that within 5 years, AWS was able to grow to $80 billion in revenues and $22.8 billion in operating income.
Despite AMZN, MSFT and GOOGL being the top players in the market there are also other well-established companies vying for market share such as IBM (IBM), Oracle (ORCL), Salesforce (CRM), etc. At the other side of the ocean there are the Chinese tech giants Alibaba (BABA), Tencent (OTCPK:TCEHY), Baidu (BIDU) and Huawei competing for market share in the Chinese cloud computing market which is set to grow to $84 billion by 2026. Even though these companies are still relatively small in regards to cloud computing compared to AMZN, GOOGL and MSFT, with time they can grow and become serious contenders. Let’s now take a look at the individual names and how they have performed!
Cloud Computing Peers (Dgtl Infra)
Amazon Web Services
AWS was launched in 2006 seeing an explosive growth since then, generating revenues of $80 billion and operating income of $22.8 billion during 2022. AWS offers a variety of services including database, storage, web & mobile apps, machine learning, etc. According to Amazon, the number of active AWS users exceeds 1 million with customers such as Goldman Sachs, Disney, Samsung, Snapchat, etc.
AWS keeps raking in big time customers, during the fourth quarter it added Yahoo Ad Tech, Brookfield Asset Management, Wallbox, American Family Insurance, etc. Further to this, AWS also launched new regions in Spain and Switzerland as well as a second region in India to continue expanding its infrastructure footprint. As of the end of 2022, AWS has 96 availability zones within 30 geographic regions globally, with announced plans to launch 15 more availability zones and 5 more AWS regions.
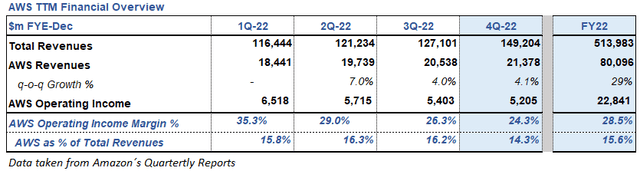
From the table above, it can be seen that AWS increased revenues by 29{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} year-over-year to $80.1 billion. Despite AWS revenues only accounting for ~16{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of AMZN total revenues AWS operating income which stood at $22.8 billion accounted for 100{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of the company’s operating income. Yes, you read that correctly, both North America and International segments recorded a loss during 2022 and AWS completely offset these losses due to its high profitability. To give another example during 2020 and 2021, AWS accounted for 74{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} and 59{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of the company’s total operating income. As you can see AMZN depends heavily on its cloud business for its growth.
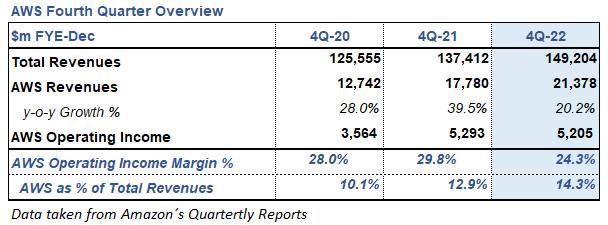
On a quarterly basis, AWS has seen a decrease on its growth rate to 20{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} from 40{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} during the fourth quarter of 2021. As it will be seen later in the article, both MSFT and GOOGL also experienced a slowdown in growth rates. Starting back in the middle of the third quarter of 2022, management started seeing growth rates slow as companies of all sizes looked into their cloud spending in response to the tough macroeconomic conditions. These optimization efforts continued into the fourth quarter and will most probably continue for next couple of quarters.
Robust Yearly Growth Continues
AWS Year over Year Financial Overview (Company´s 10-K)
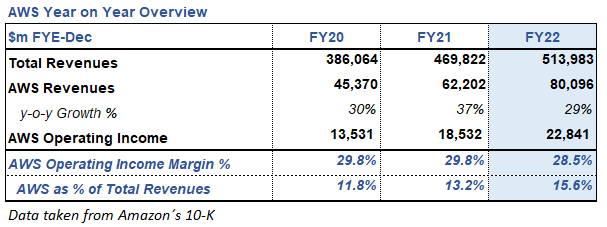
AWS was very close to double revenues within two years. During 2020 revenues stood at $45.3 billion, fast forward two years and we see revenues touching the $80 billion mark. With the market expected to continue growing to $1.2 trillion by 2027 and with AMZN investing in its global footprint, we could see AWS growing by tens of billions of dollars albeit at a slower growth rate than previous years.
MSFT Intelligent Cloud
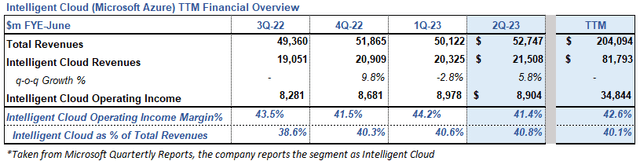
Microsoft Azure was launched in 2010, however Microsoft Intelligent Cloud segment consists of other cloud services such as SQL Server, Windows Server, Visual Studio, among others. The Intelligent Cloud segment services include databases, data storage, artificial intelligence, networking, web and mobile apps, etc. Similarly to AMZN, MSFT has also seen explosive growth during the last decade with TTM revenues standing at $81.2 billion and a whopping operating income of $34.8 billion. MSFT enjoys of a cloud computing business that constantly generates a truly spectacular operating income margin above 40{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}.
According to the company, in mid-2021 over 95 percent of Fortune 500 companies used Azure, it had over 145 million daily active users on Microsoft Teams, and over 250 thousand organizations using Microsoft Dynamics 365 and Microsoft Power Platform. Big name customers include T-Mobile, Bayer, L’Oreal, Walmart, etc.
According to Dgtl Ingfra, at the end of 2022 Microsoft Azure had 60 geographic regions globally and 116 availability zones. This numbers are substantially higher than AWS and Google Cloud which combined have 64 geographic regions. This of course gives MSFT a competitive advantage regarding its reach to lure companies across the world towards its cloud services.
Impact of MSFT Intelligent Cloud on Microsoft Overall Business
MSFT Intelligent Cloud segment increased its revenues to $81.8 billion during the TTM. MSFT Intelligent Cloud segment is quite important for Microsoft but not critical as AWS is for AMZN. The Intelligent Cloud segment now accounts for 40{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of the company’s total revenues and for 42{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of MSFT operating income. This should give MSFT shareholders a peace of mind as the business growth does not depend entirely on the cloud segment.
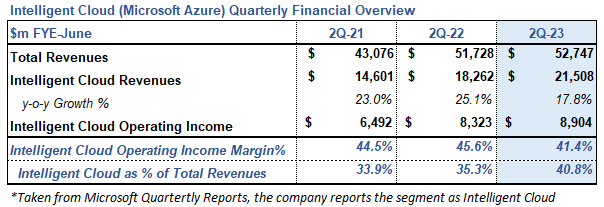
During the last quarter, revenue increased 18{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, here we can also see that the growth rate is slowing down and actually touched the teens for MSFT. However, it should be mentioned that in dollar terms the growth remained relatively flat at $3.2 billion compared to $3.6 billion during the same period last year. Further to this, during 2022 MSFT completed the acquisition of Nuance Communications. Nuance is a leader in conversational AI and ambient intelligence across industries including healthcare, financial services, retail, and telecommunications. This will help the Intelligent Cloud segment strengthen MSFT capabilities across these industries and should boost revenue growth during the coming quarters.
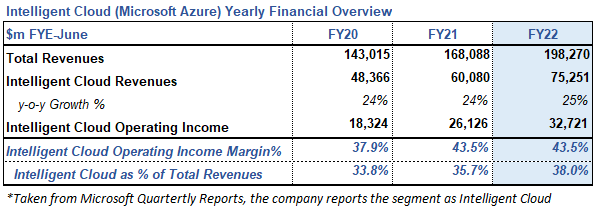
MSFT fiscal year ends in June, as such we can compare the previous 3 years and the TTM results. With this information we can see that MSFT is very close to double revenues within 3 years. During FYE 2020 revenues stood at $48.4 billion, fast forward to the end of 2022 and we see revenues at $81 billion. I think it is very important to understand that we are talking about businesses which are about to touch the $100 billion mark and are still growing at very attractive growth rates. Albeit at a weaker rate, thanks to MSFT global footprint we should continue seeing this business growing and become an even more significant part of MSFT business as a whole.
Google Cloud
Google Cloud was made available for customers at the end of 2011 and since then it has become the third largest cloud service provider globally generating revenues of $26.3 billion during 2022. Google Cloud services include databases, security, smart analytics, artificial intelligence, etc. According to Dgtl Infra, as of the end of 2022 Google Cloud has 34 regions and 103 availability zones in operation. These regions include United States, Americas, Europe, and Asia Pacific. Thanks to its global reach, Google Cloud has been able to land big name customers such as Airbus, Procter & Gamble, Carrefour, PayPal, Vodafone, Twitter, among others.
Now, it is time to address the elephant in the room, even though Google Cloud is already a big business and growing at attractive rates, it remains unprofitable. This means that the business has been unprofitable for more than a decade. We could ask ourselves, how is it that a $26 billion revenue generating business continues to be unprofitable? Well, as management has mentioned during many investors calls it all comes down to spending money in order to make money. Specifically during the latest investor call management mentioned it keeps investing ahead of revenues, these investments are significant and keep the business from becoming profitable. Let’s take a look at Google Cloud financials.
Impact of Google Cloud on Alphabet Overall Business
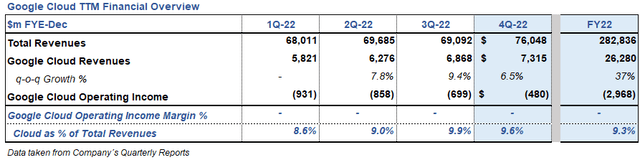
Google Cloud TTM Financial Overview (Company´s Quarterly Reports)
Google Cloud continues to increase its relevance for the company’s top line, however it has not been able to reach the 10{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} mark as of yet and as of the latest quarter results, it continues to depress the company’s overall operating income. Saying this, from the table above, we can clearly see that revenues keep increasing while operating losses continue to shrink. For example, if you compare the losses during the first quarter to the losses during the fourth quarter, these have shrunk by about 50{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}. Further to this, revenue keeps increasing at a very attractive rate, Google Cloud finished the 2022 year with a revenue increase of 37{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} compared to the previous year. Important to note that the growth rate experience by Google Cloud is above the growth rates achieved by AMZN and MSFT on yearly basis. Additionally, Google Cloud backlog continued to increase during the year, standing at $64.3 billion at the end of 2022. For reference Google Cloud backlog at the end of first quarter of 2022 stood at $50.5 billion.
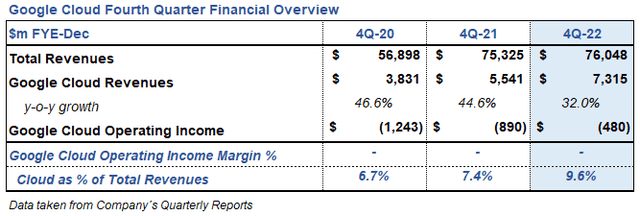
Google Cloud Fourth Quarter Financial Overview (Company´s Quarterly Reports)
During the last quarter revenue increased 32{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1}, again similarly to AMZN and MSFT, Google Cloud experienced a slowdown compared to the previous periods. Also similarly to MSFT, during 2022 management pursued an acquisition in order to boost the business. GOOGL completed the acquisition of Mandiant in Sept. 2022. Mandiant’s dynamic cyber defense, threat intelligence and incident response services are expected to enhance Google Cloud’s security offerings. Finally, the fact that Google Cloud has been able to double revenues and reduce operating losses by more than 60{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} should not go unnoticed. Even though these are still losses, the company is trending in the right direction.
Growth Continues but so do Operating Losses
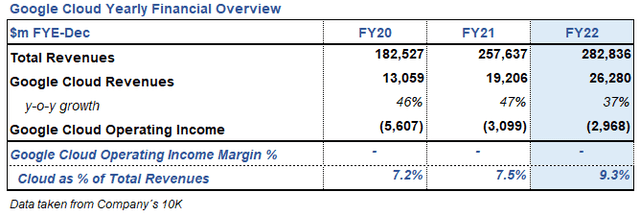
Google Cloud Yearly Financial Overview (Company´s 10-K)
Google Cloud revenues increased $7.1 billion from 2021 to 2022. This growth was primarily driven by Google Cloud Platform followed by Google Workspace offerings. Google Cloud’s infrastructure and platform services were the largest drivers of growth in Google Cloud Platform. As for the decrease in operating losses, this was mainly driven by growth in revenues. As of the end of 2022, Google Cloud is very close to reaching the 10{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} mark as a percentage of total revenues. Also, the total losses for the year are now about 50{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} of the losses experienced during 2020. It is still too early to speculate if Google Cloud will be profitable for 2023, however, it is quite possible that the business will breakeven within the next four quarters.
Google Cloud Revenue and Operating Losses Trend
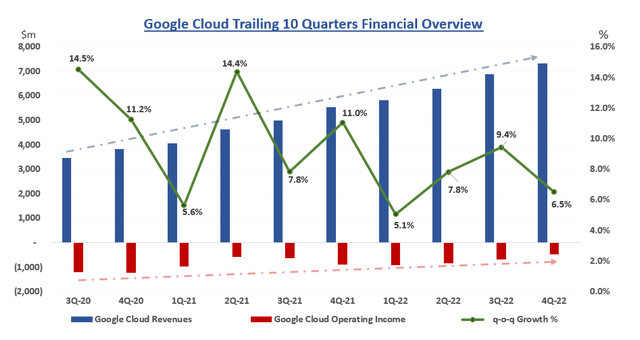
Google Cloud Trailing 10 Quarters Financial Overview (Company´s Quarterly Reports)
To finalize the Google Cloud discussion, I wanted to show the above graph so that readers can see the revenues and operating losses trends from the trailing 10 quarters. As it can be seen Google Cloud revenues have been steadily growing albeit at a slower rate during the last four quarters. It can also be seen that operating losses are volatile with some quarters experiencing higher losses than other, nonetheless the trend here is that losses are decreasing. Another interesting fact is that Google Cloud has generated revenues for GOOGL amounting to $52.8 billion during the last ten quarters, however operating losses have amounted to $8.5 billion during the same timeframe. On a final note, Google Cloud has not seen a double-digit growth rate on a quarter-on-quarter basis for four quarters now, of course with higher revenues this is more difficult to achieve. It will be interesting to see if growth rates can climb back to the rates it was experiencing two years ago.
Comparing Amazon Web Services, Microsoft Intelligent Cloud and Google Cloud
Throughout the article I have provided insights on how these three businesses have performed on a financial basis and compared their growth rates, operating income margins, etc. Saying these I believe there are a couple interesting topics to help compare these cloud providers. The first one being the global footprint these businesses have, as with a more extensive footprint they will be able to reach more customers around the globe. For example, a noticeable trait where MSFT clearly has a competitive advantage compared to AMZN and GOOGL is the extensive global footprint MSFT has. As mentioned earlier Microsoft Azure has 60 geographic regions globally, this is significantly bigger numbers than AMZN and GOOGL which both have half of the geographic regions MSFT enjoys of. This extensive global footprint by MSFT was probably a driver for acquiring more customers worldwide. AMZN is clearly trying to catch up, announcing investments in 15 more availability zones and 5 more AWS regions. We can expect Google Cloud to make similar investments in order not to fall behind.
Another great topic to discuss, is how these three companies are trying to get as many customers as possible, however it seems that the true gains that really move the needle are customers which are big companies. It is here where the cloud providers can derive significant bigger tickets and drive revenue growth. As an example, according to consultancy firm Contino, Netflix was said to be one of AMZN biggest spenders in the cloud with about $19 million back in 2020. A customer with this ticket size is really what moves the needle for these companies. As for MSFT, its biggest customer back in 2020 was Verizon with a ticket size of $80 million. Similarly, one of Google Cloud’s biggest customers back in 2020 was NewsCorp deriving revenues of $41 million. Of course much has changed since 2020, however this can give a feel of how important big spenders are for these cloud providers.
Finally, these companies are also trying to consolidate the market by acquiring companies in the space. For example during 2022, both MSFT and GOOGL made significant acquisition to bolster their cloud businesses. MSFT closed its $19.6 billion acquisition of Nuance Communications, while GOOGL closed it $5.4 billion acquisition of Mandiant. It should not come as a surprise if we keep seeing news of cloud computing companies being captured by these three leaders in the space.
Cloud Computing Market Outlook
Based on the comparative analysis of these three companies, it’s clear that both AMZN and MSFT will increasingly depend on their cloud businesses to accelerate their revenue growth and earnings. At the same time, GOOGL will try to bolster its cloud segment and seek to become profitable. Despite being the clear leaders in the space, these companies will face robust competition from companies of the likes of IBM, ORCL, CRM, BABA, TCEHY, BIDU, etc.
The pie will definitely get bigger with the global cloud computing market projected to reach over $1.2 trillion by 2027. From this, the Chinese cloud computing market alone is set to grow to $84 billion by 2026 and Asia Pacific as a whole is expected to reach $200 billion by 2024. In this region we have strong players such as BABA, TCEHY, BIDU and Huawei vying for market share, and of course we can expect these companies to try to expand their businesses all across the Asia Pacific region. Even though these companies are still relatively small compared to AMZN, GOOGL and MSFT, with time they can grow and start rivaling the US Giants.
Conclusion
This article is mainly focused on the three biggest companies in the space, but I hope it brought the readers not only a better understanding of how important cloud computing is to these companies but to all the companies in the space. The cloud computing market truly offers attractive investment opportunities, as things currently stand, I believe MSFT holds a strong competitive advantage compared to most of the companies in the space. The reasons for this are the stable and growing revenues experienced by MSFT cloud computing segment, its high operating margins constantly above 40{b7c9e2c88beb1a84f22d94ab877a147f4adc4b3519717f3f957a0f34e16918d1} as well as its advantage due to its extensive global footprint. This does not mean MSFT is the only investment opportunity, but it provides a certain security factor compared to other companies in the space. I recommend that investors consider looking more deeply into companies in the cloud computing space and consider the potential of gaining exposure to this growing market.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Microsoft Corp is revamping its Bing research motor and Edge world wide web browser with artificial intelligence, the firm explained on Tuesday, in 1 of its largest endeavours yet to lead a new wave of know-how and reshape how persons obtain facts.
Microsoft is staking its future on AI by billions of pounds of expenditure as it straight issues Alphabet Inc’s Google. That could mean new level of competition for enterprise customers making use of cloud and collaboration merchandise as nicely as a vigorous return to buyer marketplaces wherever Google now qualified prospects.
Working with the startup OpenAI, Microsoft is aiming to leapfrog its rival and most likely declare large returns from equipment that velocity up all fashion of material creation, automating duties, if not careers themselves.
“This technologies is likely to reshape rather significantly just about every computer software classification,” Microsoft Main Executive Satya Nadella instructed reporters in a briefing at Microsoft headquarters in Redmond, in Washington state.
Some investors hope the technologies to produce new marketplaces even as Massive Tech providers compete for dominance. Shares of Microsoft rose 3.8 p.c in afternoon trading, and Alphabet acquired 3.6 per cent.
The ability of so-named generative AI, which can produce almost any text or graphic, dawned on the community last yr with the launch of ChatGPT, the chatbot feeling from OpenAI. Its human-like responses to any prompt have supplied persons new means to consider about the possibilities of advertising and marketing, writing term papers or disseminating information, or even how to question info on the net.
The new Bing search engine is are living in minimal preview on desktop pcs and will be out there for cell devices in coming months.
Bing will be driven by AI and operate on a new “large language model” that is extra highly effective than ChatGPT, said Microsoft Buyer Main Marketing and advertising Officer Yusuf Mehdi. A chatbot will assistance customers refine queries additional quickly, give much more pertinent, up-to-day outcomes, and even make browsing simpler.
Bing is significantly guiding Google in look for industry share.
Microsoft is now aiming to market OpenAI’s know-how, like ChatGPT, to its cloud consumers and add the exact electrical power to its suite of merchandise, including research.
In close proximity to-expression, “the partnership with OpenAI is more appropriate for its company shoppers,” explained Gartner analyst Jason Wong. Still, he mentioned, it could offer “disruptive opportunities” in shopper corporations as well.
“Except for gaming, Microsoft has not been a leader in important shopper systems, such as search, cellular and social media,” he extra.
Google has taken note. On Monday, it unveiled a chatbot of its very own termed Bard, though it is planning to release AI for its lookup motor that can synthesize product when no simple remedy exists on the internet.
Microsoft’s determination to update its Edge browser will intensify competition with Google’s Chrome browser.
The rivalry in lookup is now amid the industry’s biggest, as OpenAI sets up Microsoft to grow its 9 percent share at Google’s cost, stated Daniel Ives, an analyst with Wedbush Securities.
Functional takes advantage of
At the celebration, Mehdi shown how the AI-enhanced lookup motor will make searching and developing e-mail less complicated. A demonstration showed how Bing could estimate, for illustration, whether or not a certain kind of sofa could fit in the again of a motor vehicle by pulling with each other World wide web facts on one’s car proportions.
For the quarter ending December 31, Alphabet reported $42.6bn in Google Lookup and other revenue, while Microsoft posted $3.2bn from search and news advertising and marketing.
Powering Microsoft’s OpenAI partnership is its prepare to commit in supercomputer development and cloud aid so the startup can launch more advanced technological know-how and goal at the stage of device intelligence dreamed up in science fiction.
The fruit of this function, however, is additional instant. Very last 7 days Microsoft announced the startup’s AI will create conference notes in Teams, its collaboration computer software, as properly as propose email replies to distributors utilizing its Viva Sales membership.